Property must be located within an area currently eligible for USDA financing.
USDA Home Loans With No Down Payment
Buy with no down payment in eligible rural and suburban areas. Designed for moderate-income buyers in qualifying locations. Available across our seven licensed states.
Independent Brokerage, Many Lenders
Licensed in 7 States
NMLS #2367229
Decades of Combined Experience
What Is a USDA Home Loan?
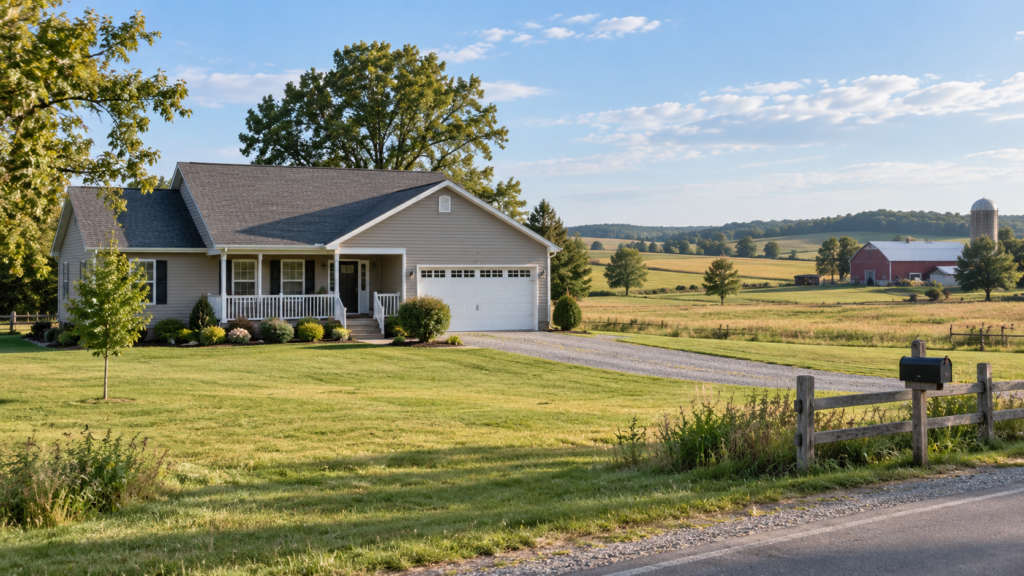
A USDA loan is a government-backed mortgage insured by the U.S. Department of Agriculture. It allows eligible buyers to purchase a primary residence with zero down payment in qualifying rural and suburban areas.
USDA loans offer competitive fixed interest rates and lower monthly mortgage insurance compared to FHA loans.
What Are the Property Requirements for a USDA Loan?
To qualify for a USDA loan, the property must meet certain requirements, including:
Located in an Eligible USDA-Designated Area
Used as the Buyer's Primary Residence
Home must serve as the buyer’s primary residence after the loan closes.
Meet Basic Safety and Livability Standards
Property must meet applicable safety, structural, and livability requirements for loan approval.
USDA loans are not available for investment properties or vacation homes.
What Are the Benefits of a USDA Home Loan?
USDA loans offer several advantages that make them an attractive option for eligible buyers:
No Down Payment Required
Eligible buyers may be able to finance a home with no down payment.
Competitive Fixed Interest Rates
USDA loans offer fixed-rate financing that can provide predictable monthly principal and interest payments.
Lower Monthly Mortgage Insurance
Monthly mortgage insurance may be lower compared with some other loan programs.
Flexible Credit Guidelines
USDA loans can offer more flexible credit requirements for eligible borrowers.
Affordable Monthly Payments
USDA financing can help keep monthly housing costs more manageable for qualified buyers.
These features can help eligible buyers keep upfront and monthly housing costs more manageable.
Who Qualifies for a USDA Loan?
USDA loan eligibility is based on a combination of factors, including:
Property Location
The property must be located within an eligible USDA-designated area.
Household Income Limits
Household income must fall within the applicable USDA limits for the area.
Citizenship or Eligible Residency
Borrowers must meet applicable USDA citizenship or eligible residency requirements.
Credit and Income Stability
Borrowers should demonstrate stable credit and income to meet USDA qualification requirements.
Is a USDA Loan Right for You?
A USDA loan is a strong option for buyers in qualifying areas who want to purchase a home with no down payment. Income limits and property location requirements apply.
Many suburban areas may qualify, even when buyers do not expect them to. We confirm your property and income eligibility and compare USDA options against other zero-down programs so you choose the right fit.
One Broker. Many USDA Loan Options.
A bank can only offer what that bank sells. If their USDA pricing or eligibility overlay is uncompetitive this week, you will never hear about it, because they have no reason to tell you.
We are independent. We compare USDA loan options across our lender network and show you the rate, fees, credits, and cash to close side by side.
If FHA, VA, or conventional financing fits you better, we will tell you that too.
Questions Buyers Ask About USDA Loans
What is a USDA loan?
A USDA loan is a mortgage guaranteed by the United States Department of Agriculture for properties in eligible rural and suburban areas. It requires no down payment for qualified buyers and carries guarantee fees that are generally lower than FHA mortgage insurance. It is one of the most overlooked programs available.
Do I have to live on a farm to get a USDA loan?
No. The program is about location, not agriculture. It covers ordinary single-family homes in designated areas, and far more neighborhoods qualify than most buyers expect. Many towns on the edge of a metro area are eligible, including communities across the mid-Willamette Valley in Oregon.
Which areas qualify for a USDA loan in Oregon?
Eligibility is set by USDA maps rather than by county, and the boundaries can run down the middle of a neighborhood. Smaller communities around Salem, Albany, and Corvallis frequently qualify while the city centers do not. Send us the address and we will check the specific property before you go further.
Is there an income limit for a USDA loan?
Yes. USDA loans carry household income limits that vary by county and household size, and they count the income of adults in the household rather than only the borrowers. The limits are more generous than most people assume. We check your household against the limit for your county early so nothing surprises you.
How much down payment does a USDA loan require?
None. Eligible buyers can finance 100 percent of the purchase price. There are still closing costs, though seller concessions, lender credits, and in some cases financing the guarantee fee can reduce what you bring to the table. We will show you the real cash-to-close number.
Does a USDA loan have mortgage insurance?
It carries an upfront guarantee fee and an annual fee paid monthly, which function similarly to mortgage insurance. Both are generally lower than the equivalent FHA premiums, which is a large part of why USDA is worth checking before defaulting to FHA on an eligible property.
What credit score do I need for a USDA loan?
Most lenders look for a score in the low 600s, though the program has flexibility and the rest of the file matters. Income stability, debt load, and the property all factor in. Because lender requirements differ, comparing across our network often changes the answer.
How long does it take to close a USDA loan?
Closing takes 21 to 30 days in most cases once you have an accepted offer and your documents are in, though USDA files involve a guarantee step that can add time in busy periods. We are licensed in Oregon, California, Washington, Idaho, Texas, Florida, and Montana, with offices in Salem and Eugene, Oregon.
Compare Your USDA Loan Options
USDA eligibility depends on the property location, household income, credit profile, and other program requirements. We will check the property and your eligibility, then explain the available financing options and estimated cash needed to close.