Finance a home above the conforming loan limit with competitive rates and flexible terms. For buyers purchasing above the conforming loan limit of $832,750 in most markets. Available across our seven licensed states.
A jumbo loan is a mortgage that exceeds the applicable conforming loan limit for the property’s county. Conforming loan limits are set annually by the Federal Housing Finance Agency and can vary by location. Because jumbo loans are not eligible for purchase by Fannie Mae or Freddie Mac, lenders may apply stricter credit, income, down-payment, and cash-reserve requirements.
Who Qualifies for a Jumbo Loan?
Jumbo-loan qualification often involves a detailed review of your financial profile. Depending on the lender and loan scenario, factors may include:
Strong Credit History
A strong credit history can help support qualification for a jumbo loan and access to available loan options.
Verifiable Income
Consistent, verifiable income helps demonstrate the ability to support a larger mortgage amount.
Manageable Debt Levels
Low to moderate debt relative to income can strengthen your overall jumbo loan qualification profile.
Significant Asset Reserves
Lenders may look for significant reserves to confirm additional financial strength beyond the down payment.
Equity or Down Payment
Sufficient home equity or a qualifying down payment may be required depending on the loan and property scenario.
Because jumbo loans exceed conforming loan limits, underwriting standards can be more conservative than for conforming loans. A personalized review can help clarify your available options and likely qualification path.
JUMBO LOAN BENEFITS
What Are the Benefits of a Jumbo Loan?
Jumbo loans offer several features that appeal to buyers of higher-value homes:
Single-Loan Financing
Finance a higher-value home with one jumbo mortgage instead of combining multiple loans.
Flexible Term Options
Choose from available loan terms that align with your budget, goals, and long-term plans.
Fixed and Adjustable Rate Choices
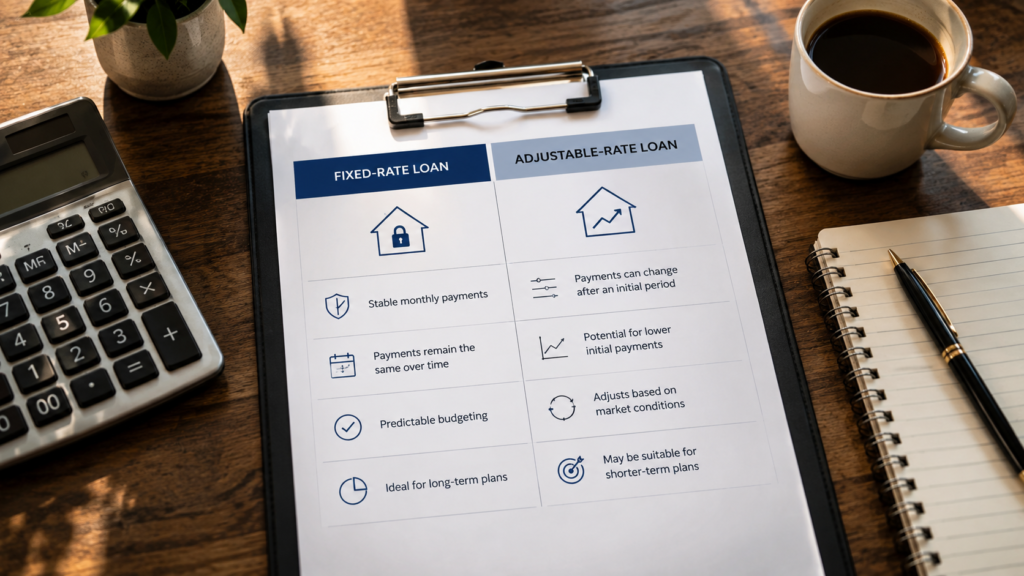
Select a fixed or adjustable-rate structure based on your payment preferences and financial strategy.
Access to Larger Amounts of Capital
Finance a higher-value property when the loan amount exceeds the conforming limit for your area.
These benefits make jumbo loans a strong option when conventional limits don’t meet your needs.
JUMBO LOAN UNDERWRITING
How Does Jumbo Loan Underwriting Differ From a Conforming Loan?
Because jumbo loans exceed conventional limits, lenders look more closely at financial strength. Typical review factors include:
Credit Profile and Score
Strong credit improves approval chances.
Stable Income and Employment History
Lenders generally look for consistent, verifiable income and employment stability.
Debt-to-Income Ratio
Debt levels are reviewed in relation to income and the larger loan amount.
Asset Reserves
Lenders often require enough reserves to cover several months of payments after closing.
Lenders assess these details to help ensure that the loan is sustainable based on your overall financial position.
MAKING THE DECISION
Is a Jumbo Loan Right for You?
A jumbo loan is the right option when the home you are buying exceeds the conforming loan limit for your county. Strong credit, consistent income, and sufficient asset reserves are required.
We compare jumbo loan options across multiple lenders so you find the most competitive rate for your financial profile.
A bank can only offer the jumbo programs available through that bank. With jumbo financing, lender guidelines, reserve requirements, loan structures, and pricing can vary significantly.
Mortgage Marketplace is independent. We compare jumbo loan options across our lender network based on your property, financial profile, loan amount, and goals. That gives you more choices and a clearer side-by-side view of the available options.
If another loan structure fits your situation better, we will tell you that too.
A jumbo loan is a mortgage for properties that exceed the conforming loan limit set by Fannie Mae and Freddie Mac. That limit is $832,750 in most markets. Loan amounts above the conforming limit for your county require a jumbo loan. Because jumbo loans are not government-backed, lenders apply stricter credit, income, and reserve requirements. Most programs require a credit score of 700 or higher and a down payment of 10% to 20%.
What credit score do I need for a jumbo loan?
Jumbo loans typically require a stronger credit profile than conventional loans. Most lenders look for a credit score of 700 or higher, though some programs allow lower scores with compensating factors such as larger down payments or significant reserves. The stronger your credit profile, the more competitive your rate options may be.
How much down payment does a jumbo loan require?
Jumbo loans generally require a higher down payment than conventional loans. Most programs require 10% to 20% down depending on the loan amount, property type, and borrower profile. Some programs allow lower down payments for borrowers with very strong credit and reserve profiles. Your specific requirement will be confirmed during the review process.
Can I get a jumbo loan for an investment property?
Yes, jumbo loans are available for investment properties as well as primary residences and second homes. Qualification requirements for investment property jumbo loans are typically stricter than for primary residences. Down payment and reserve requirements are usually higher for non-owner-occupied properties.
Ready to Explore Jumbo Loan Options?
We compare Jumbo Loan programs across multiple lenders so you get competitive rates on high-value home financing. Licensed in OR, CA, WA, ID, TX, FL, and MT.