Qualification depends on how much equity you have built in your home compared with your current mortgage balance.
LOAN PROGRAM
Home Equity Loans and Lines of Credit
Tap your home equity without replacing your current mortgage. Compare HELOC and home equity loan options side by side. Available across our seven licensed states.
Independent Brokerage, Many Lenders
Licensed in 7 States
NMLS #2367229
Decades of Combined Experience
HOME EQUITY FINANCING
What Is Home Equity Financing?
Home equity financing lets homeowners borrow against the equity they have built in their property. Equity is the difference between your home’s current value and what you still owe on your mortgage. It comes in two forms: a home equity loan, which gives you a lump sum at a fixed rate, or a HELOC, which gives you a revolving credit line at a variable rate. Neither option replaces your existing first mortgage.
What Do I Need to Qualify for a Home Equity Loan or HELOC?
Qualification typically depends on:
Available Home Equity
Credit Profile
Lenders review your credit profile to evaluate eligibility, loan terms, and available home equity options.
Income and Ability to Repay
Lenders consider your income, debts, and overall ability to repay the loan based on program guidelines.
Property Type and Occupancy
Eligibility may vary based on the type of property and whether the home is owner-occupied.
Loan limits and terms vary by lender and program.
HOME EQUITY OPTIONS
How Does a Home Equity Loan Differ From a HELOC?
Home Equity Loan
A home equity loan provides a lump-sum payout with a fixed interest rate and predictable monthly payments.
- Fixed interest rate
- Lump-sum payout
- Predictable monthly payments
Home Equity Line of Credit (HELOC)
A HELOC provides a revolving credit line with a variable interest rate, allowing you to access funds as needed.
- Revolving credit line
- Variable interest rate
- Funds accessed as needed
The right option depends on how you plan to use the funds and your preference for payment stability.
COMMON USES
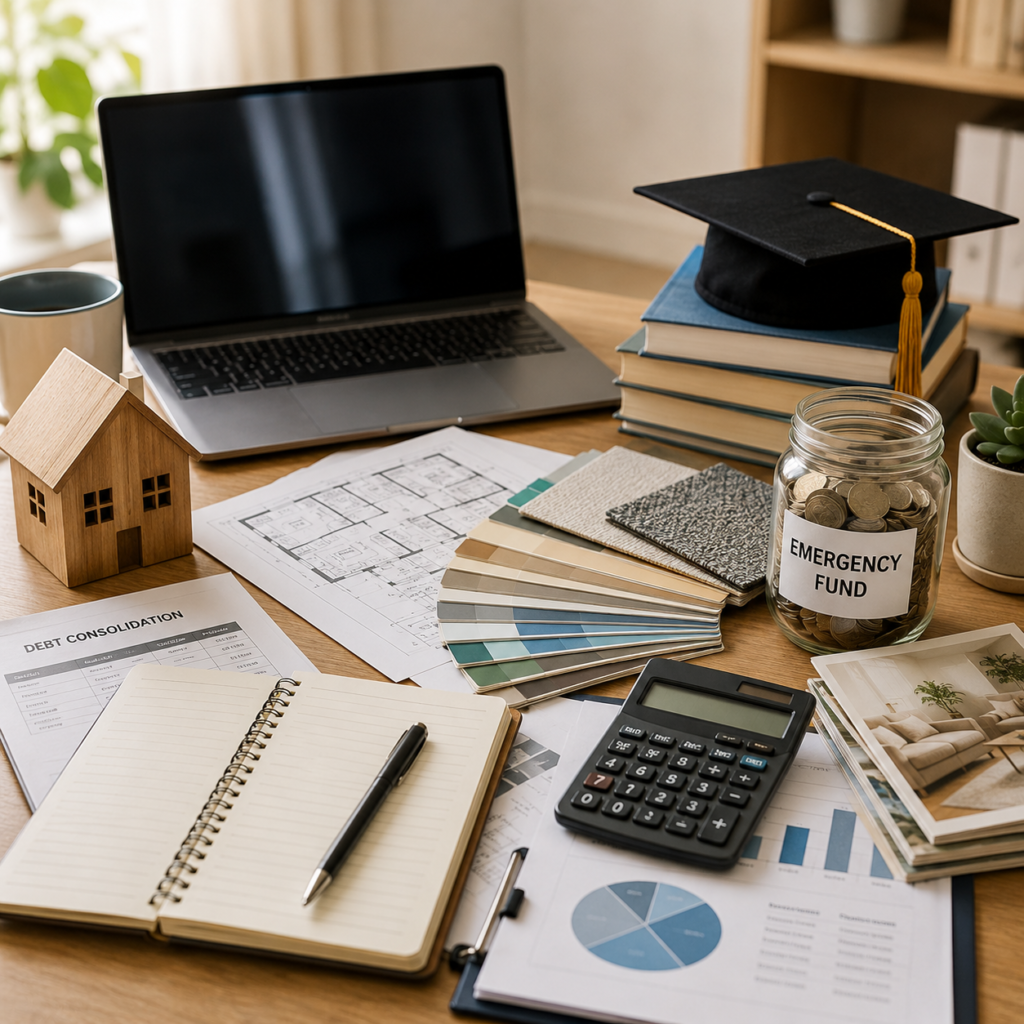
How Can Homeowners Use Home Equity?
- Home improvements or renovations
- Debt consolidation
- Education expenses
- Major purchases
- Emergency reserves
Using home equity strategically can provide flexibility without refinancing your primary mortgage.
MAKING THE DECISION
Is Home Equity Financing Right for You?
A home equity loan or HELOC is a strong option when you need to access cash without refinancing your first mortgage. Your home secures the loan, so repayment is required.
We compare your options across multiple lenders so you see the real numbers before you decide.
THE BROKER ADVANTAGE
One Broker. Many Home Equity Options.
A bank can only offer the home equity products available through that institution. If its HELOC or home equity loan terms are not competitive, you may never see the alternatives.
We are independent. We compare home equity options across our lender network, including rates, fees, loan structure, draw terms, and repayment requirements, so you can see the differences before deciding.
If a cash-out refinance or another financing option makes more sense for your situation, we will tell you that too.
HOME EQUITY FAQ
Questions Homeowners Ask About Equity
What is the difference between a home equity loan and a HELOC?
A home equity loan is a lump sum at a fixed rate with a fixed payment, which suits a one-time expense with a known cost. A HELOC is a revolving line you draw against as needed, usually at a variable rate, which suits ongoing or uncertain costs. Both are secured by your home.
How much can I borrow against my home?
Most lenders allow you to borrow up to a combined loan-to-value of 80 to 90 percent, counting your existing mortgage plus the new loan. On a $400,000 home with a $200,000 mortgage, that commonly puts $120,000 to $160,000 within reach. Your credit, income, and the property determine where you land in that range.
Should I take a HELOC or a cash-out refinance?
If your existing mortgage carries a low rate, a HELOC or home equity loan lets you keep it while accessing equity, which is usually the better choice. If your current rate is high or you want everything in one payment, a cash-out refinance may cost less overall. We compare both on your actual numbers before recommending either.
What can I use the money for?
Anything, though the most common uses are home improvements, debt consolidation, education costs, and covering a gap between buying and selling. Using equity to pay off high-interest debt can lower your total monthly outflow substantially, though it converts unsecured debt into debt secured by your home. That trade-off deserves a clear-eyed look.
How does a HELOC draw period work?
A HELOC typically has a draw period during which you can borrow and repay repeatedly, often making interest-only payments, followed by a repayment period when the balance amortizes and the payment rises. Understanding when that shift happens, and what the payment becomes, is essential before you open one.
Is the interest tax deductible?
It may be, depending on how the funds are used and your individual tax situation. We are not tax advisors and cannot give tax advice. Speak with a qualified tax professional about your circumstances before making a decision on that basis.
What credit score do I need for a HELOC?
Most lenders look for a score in the mid 600s or higher, with better pricing above 700. Available equity, income stability, and debt load all factor in alongside credit. Requirements vary meaningfully between lenders, so a decline at one institution is not the end of the conversation.
How long does it take to get a home equity loan or HELOC?
Closing takes 21 to 30 days in most cases. Some programs move faster than a first mortgage because the documentation is lighter. We are licensed in Oregon, California, Washington, Idaho, Texas, Florida, and Montana, with offices in Salem and Eugene, Oregon.
Compare Your Home Equity Options
Home equity loan and HELOC options vary based on equity, credit, and lender guidelines. We compare your options across multiple lenders so you see the real numbers before you decide.