Is 2026 the Right Year to Refinance Your Home in Salem, OR?
As we settle into 2026, the real estate landscape in Salem, OR and across the Pacific Northwest is witnessing a welcome shift. After periods of volatility, interest rates are showing signs of stabilization, creating a unique window of opportunity for homeowners. If you purchased your home during the peak rate environments of previous years, or if your home equity has grown significantly, now might be the perfect time to evaluate your mortgage strategy.
At Mortgage Marketplace, we understand that refinancing isn’t just about chasing a lower number; it’s about aligning your mortgage with your long-term financial goals. Whether you are looking to lower your monthly overhead, shorten your loan term, or access cash for renovations, understanding the 2026 market dynamics is crucial. This guide explores why stabilizing rates matter and how local homeowners can benefit.
Top Benefits of Refinancing in a Stabilized Market
Refinancing in a stable market offers more than just interest savings. Here is how a strategic refinance can transform your financial picture:
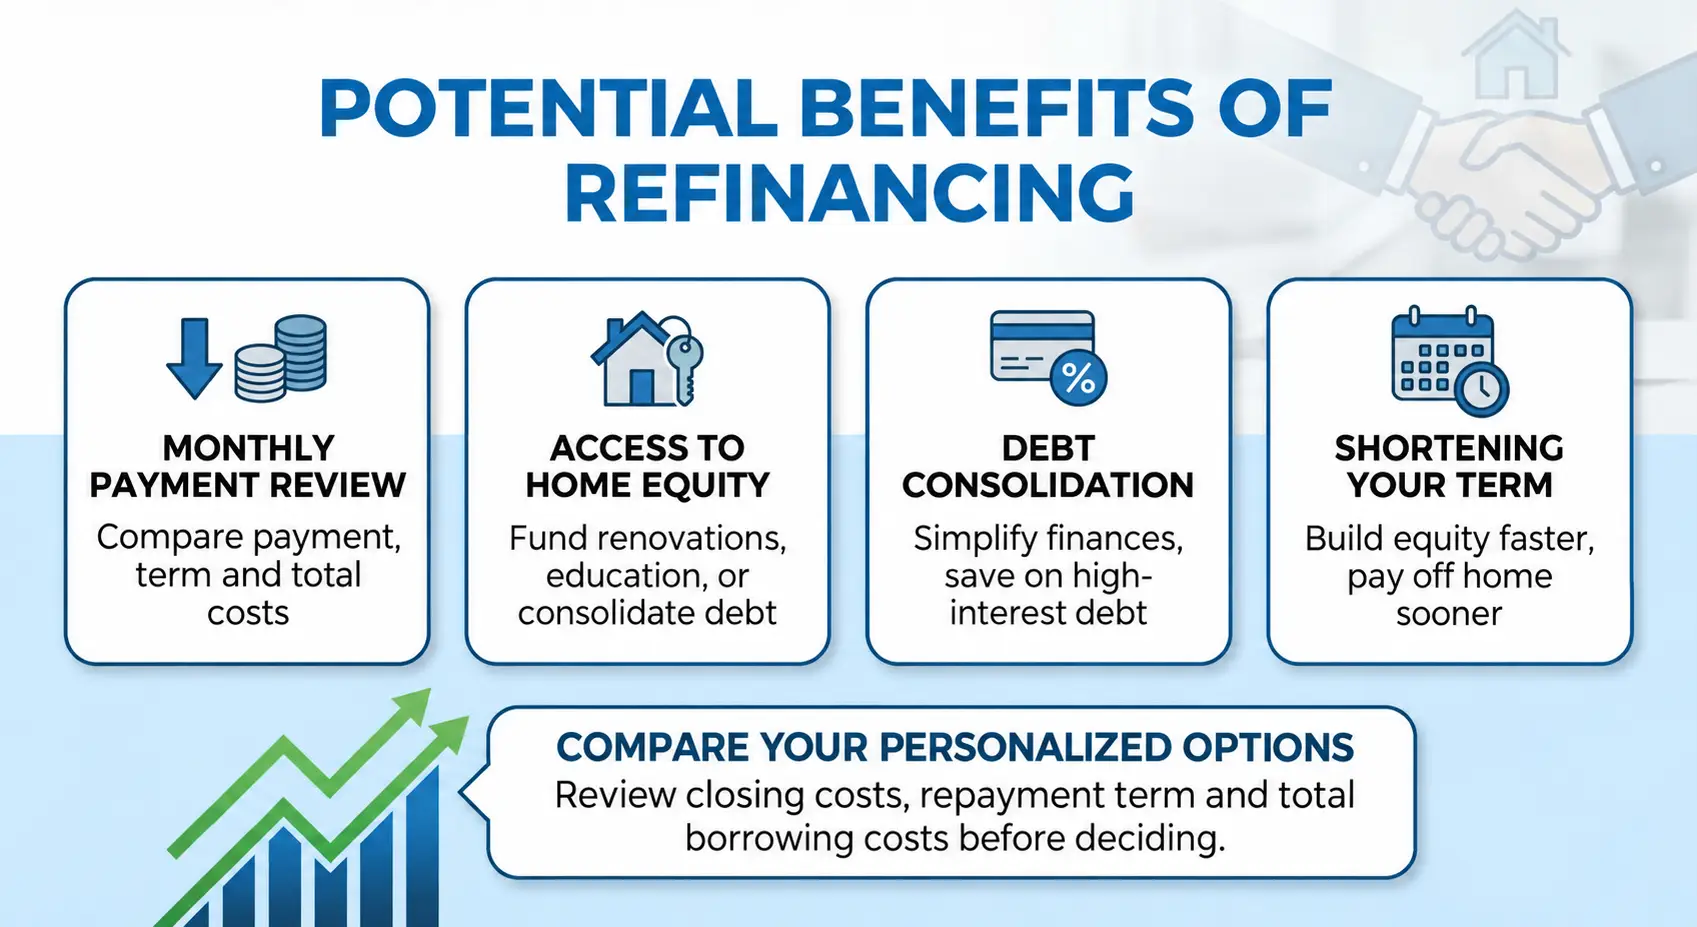
- Lower Monthly Payments: A refinance may reduce your monthly payment, depending on the new terms, closing costs and repayment period.
- Access to Home Equity: With property values in Salem holding steady or increasing, a cash-out refinance allows you to tap into your home’s equity to fund major renovations, pay for education, or consolidate high-interest debt.
- Debt Consolidation: By rolling high-interest credit card debt into a lower-rate mortgage, you can simplify your finances and potentially reduce interest costs over time.
- Shortening Your Term: If your income has increased, switching from a 30-year to a 15-year fixed-rate mortgage can help you build equity faster and pay off your home sooner.
Consulting with an expert like Mike Gillett can help you determine which benefit aligns best with your current situation.
| Loan Scenario | Rate Structure | Monthly Principal & Interest | Long-Term Cost Review |
|---|---|---|---|
| Current Loan | Review your existing terms | Review your current statement | Consider remaining interest and repayment term |
| Potential Refinance | Compare personalized lender options | Compare the proposed payment and term | Include closing costs and total repayment costs |
| Decision Factors | Terms depend on your circumstances | Assess affordability and cash flow | Compare the break-even period with your plans |
Strategic Refinancing: Timing Your Move with Mortgage Marketplace
Timing is everything when it comes to refinancing. While market rates are a major factor, your personal financial health is equally important. To maximize the benefits of a refinance in 2026, consider the following strategies:
- Monitor Your Break-Even Point: Calculate how long it will take for your monthly savings to offset the closing costs. If you plan to stay in your Salem home past this point, refinancing makes financial sense.
- Improve Your Credit Score: Credit history can affect the rates and terms lenders offer. Review your report and address any discrepancies before applying.
- Evaluate Your Equity Position: Generally, having at least 20% equity helps you avoid Private Mortgage Insurance (PMI) and qualify for better terms.
At Mortgage Marketplace, we offer a personalized Refinance Analysis to help you visualize these scenarios. We compare options across multiple lenders to ensure you aren’t just fitting into a bank’s box, but finding a solution tailored to you.
Q1: What is the ideal credit score for refinancing in 2026?
While requirements vary by loan type (FHA, VA, Conventional), credit requirements and available terms depend on the lender, loan program and your full financial profile. Ask a loan officer about options for your circumstances.
Q2: How much equity do I need to refinance my home in Salem?
Most lenders prefer you to have at least 20% equity to avoid mortgage insurance, but programs like FHA and VA refinances have more flexible equity requirements.
Q3: Can I get cash out for home improvements while refinancing?
Yes, a cash-out refinance allows you to replace your current mortgage with a larger one, giving you the difference in cash to fund renovations or other expenses.
Q4: How long does the refinance process take with Mortgage Marketplace?
With our streamlined process and proactive planning, most refinances close in less than 30 days, provided all documentation is submitted promptly.
Q5: Are closing costs worth paying for a lower rate?
It depends on your break-even point. If you plan to stay in the home long enough for the monthly savings to exceed the upfront costs, it is usually a smart financial move.


