Minimum credit score requirements vary depending on the loan structure and lender guidelines.
LOAN PROGRAM
Medical Professional Home Loan Program
Finance your home with no down payment and no mortgage insurance, qualified on your career path rather than a long income history. Built for physicians and eligible healthcare professionals. Available across our seven licensed states.
Independent Brokerage, Many Lenders
Licensed in 7 States
NMLS #2367229
Decades of Combined Experience
PROGRAM OVERVIEW
What Is a Medical Professional Loan Program?
The Medical Professional Loan Program is a specialized mortgage option for physicians and other eligible healthcare professionals who may be purchasing a home before establishing a traditional income history. Depending on the lender and program guidelines, qualification may consider employment contracts, professional credentials, and projected income in addition to traditional employment history.
Features such as high loan-to-value financing, mortgage-insurance options, and flexible underwriting may be available to qualified residents, fellows, and newly employed physicians, subject to lender and program requirements.
What Flexible Qualification Options May Be Available?
Qualification requirements vary by lender and loan structure. Depending on the lender and program guidelines:
- A limited credit history may be considered.
- Certain business funds may be considered for qualification.
- Student-loan treatment may vary.
- Signed employment contracts and projected income may be considered.
What Loan Structures May Be Available?
Medical professional loan programs may offer both fixed-rate and adjustable-rate options, depending on the lender, loan structure, and borrower qualifications.
- Fixed-rate terms available: 15, 20, 25, and 30 years
- ARM options available: 5/6, 7/6, and 10/6 structures
What Properties May Be Eligible?
Property eligibility varies by lender and program. Qualified borrowers may have financing options for several common residential property types and sizes.
- 1-unit homes, warrantable condos, PUDs, and modular homes allowed
- Properties up to 40 acres eligible
- Appraisal transfers accepted
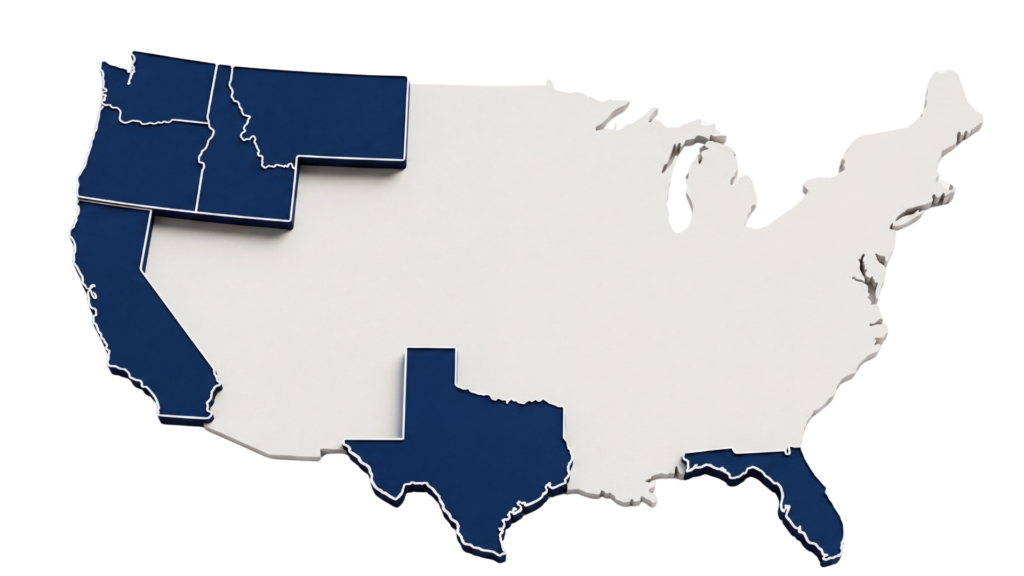
Mortgage Marketplace is licensed to help medical professionals purchase homes in Oregon, California, Washington, Idaho, Texas, Florida, and Montana.
PROGRAM BENEFITS
What Are the Benefits of a Medical Professional Loan Program?
This program is designed to remove common barriers that medical professionals face when applying for a mortgage:
Up to 100% financing available for qualified borrowers
No mortgage insurance requirement
Flexible underwriting tailored to medical career paths
Options for purchases and refinances
Ability to use signed employment contracts for qualification
Competitive fixed and adjustable-rate options
Available for primary residences in eligible areas
QUALIFICATION GUIDELINES
What Should Medical Professionals Know About Qualification?
This program qualifies borrowers based on professional credentials and employment stability rather than traditional income history. A minimum credit score of 680 is required. Only one tradeline is needed for qualification. Student loans may be excluded from debt-to-income calculations. Signed employment contracts are accepted in place of pay stubs for newly employed physicians.
ELIGIBLE PROFESSIONALS
Which Medical Professionals May Be Eligible?
- Medical Doctor (MD)
- Doctor of Osteopathy (DO)
- Doctor of Dental Science or Surgery (DDS)
- Doctor of Dental Medicine (DMD)
- Doctor of Ophthalmology (MD or DO)
- Doctor of Psychiatry (MD or DO)
- Doctor of Veterinary Medicine (DVM or VMD)
- Doctor of Podiatric Medicine (DPM)
- Doctor of Pharmacy (PharmD)
- Certified Registered Nurse Anesthetist (CRNA)
- Medical residents, fellows, or interns with one of the above degrees
ADDITIONAL REQUIREMENTS
What Additional Qualification Factors Apply?
Credit Requirements
Income & Employment Review
Debt-to-income evaluation may consider signed employment contracts and projected income.
Flexible Student Loan Treatment
Student loan obligations may receive flexible treatment where program and lender guidelines allow.
Primary Residence Financing
Financing is available for eligible 1-unit properties that will be used as the borrower’s primary residence.
MAKING THE DECISION
Is the Medical Professional Loan Program Right for You?
This program is designed for medical professionals who want to purchase a home without delaying their plans due to traditional income timelines or large down payment requirements. It supports those transitioning from training to practice by offering flexible qualification methods that reflect the realities of a medical career.
A personalized review helps determine whether this financing approach fits your goals, timeline, and long-term financial strategy so you can move forward with clarity and confidence.
THE BROKER ADVANTAGE
One Broker. Many Medical Professional Loan Options.
We are independent. We compare medical professional loan programs across our lender network and help you understand the qualification requirements, financing structure, and available options side by side.
If a conventional loan, jumbo loan, or another mortgage program fits your situation better, we will tell you that too.
PHYSICIAN LOAN FAQ
Questions Physicians and Dentists Ask
What is a physician home loan?
A physician loan, sometimes called a medical professional loan, is a mortgage designed around how medical careers actually work. It typically allows low or no down payment without mortgage insurance and treats student loan debt differently than standard underwriting, recognizing high future earnings against high current debt.
Who qualifies for a medical professional loan?
Eligibility varies by lender but commonly includes physicians, dentists, veterinarians, and in some programs physician assistants, nurse practitioners, pharmacists, and optometrists. Residents and fellows are often eligible before their attending income begins. Tell us your credential and stage and we will confirm which lenders include you.
Can I get a physician loan during residency?
Often yes. Many programs accept a signed employment contract with a start date in the near future in place of pay stubs, which allows you to buy before your first paycheck arrives. This is one of the most useful features of the program for anyone relocating for a residency or a new position.
How is my student loan debt treated?
Physician programs commonly exclude deferred student loans or use a reduced payment calculation rather than the full standard payment. That single difference is often what makes the purchase possible on a file that conventional underwriting would decline. The exact treatment varies by lender.
Do physician loans require mortgage insurance?
Most do not, even with a low down payment. That is the second major advantage over a conventional low-down-payment loan, and over the life of the loan it can be worth a great deal. Program terms differ, so the comparison is worth running against a conventional option.
Are physician loan rates higher?
Sometimes slightly, and sometimes not at all. The absence of mortgage insurance frequently offsets any rate difference, so comparing the monthly payment and the total cost matters more than comparing the rate alone. We run the physician program against conventional and jumbo on your actual numbers.
How much can I borrow with a physician loan?
Many programs extend well into jumbo territory without requiring a jumbo down payment, which is why they suit higher-value purchases. Limits vary by lender and by your stage of career. We will confirm the ceiling for your situation before you start looking at homes.
How long does it take to close a physician loan?
Closing takes 21 to 30 days in most cases. If you are relocating for a new position, start the conversation well before your move date. We are licensed in Oregon, California, Washington, Idaho, Texas, Florida, and Montana, with offices in Salem and Eugene, Oregon.
Review Your Medical Professional Loan Options
Program requirements and benefits vary based on your financial profile, employment structure, and property details. Start with a personalized review to explore available options and compare them with other loan programs that may fit your situation.