Financing for standalone rental properties based primarily on the property’s rental income.
LOAN PROGRAM
DSCR Loans for Real Estate Investors
Qualify on the property’s rental income, not your personal tax returns. Built for real estate investors buying or refinancing rentals. Available across our seven licensed states.
Independent Brokerage, Many Lenders
Licensed in 7 States
NMLS #2367229
Decades of Combined Experience
DSCR PROPERTY ELIGIBILITY
What Is a DSCR Loan?
A DSCR loan qualifies you based on a rental property’s income rather than your personal tax returns, W-2s, or employment history. Lenders calculate your Debt Service Coverage Ratio by dividing the property’s gross monthly rent by its total monthly housing expense. A ratio of 1.0 means the rent covers the payment exactly. Most programs prefer a ratio of 1.2 or higher.
What Property Types May Be Eligible for a DSCR Loan?
DSCR loans may be available for:
Single-Family Rental Homes
Condos and Townhomes
Eligible condo and townhome investments may qualify depending on the property and program guidelines.
Multi-Unit Properties
DSCR financing may be available for qualifying residential properties with multiple rental units.
Short-Term Rental Properties
Short-term rental properties may qualify depending on the program, location, and documented rental income.
Eligibility depends on property type, location, and rental income documentation.
DSCR LOAN EVALUATION
How Are DSCR Loans Evaluated?
DSCR is calculated by comparing the property’s gross rental income to its monthly housing expenses, including principal, interest, taxes, insurance, and HOA dues if applicable.
DSCR of 1.0
Rental income covers the property’s monthly housing payment.
Higher DSCR Ratios
Stronger coverage ratios may provide access to more favorable loan terms.
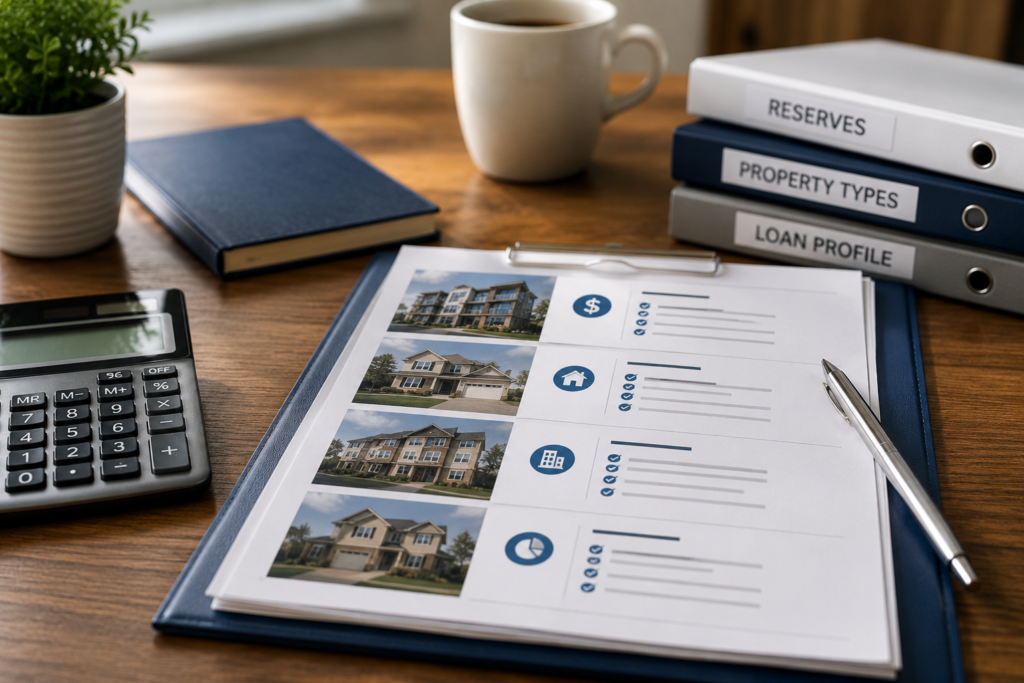
Program Flexibility
Some programs allow flexibility based on reserves, property type, and the overall loan profile.
Loan guidelines vary by lender and property profile.
DSCR INVESTOR PROFILE
Who Are DSCR Loans Designed For?
DSCR loans are commonly used by:
Real Estate Investors
Investors financing income-producing residential rental properties.
Rental Property Buyers
Buyers purchasing properties intended to generate rental income.
Short-Term & Long-Term Rental Owners
Financing options for qualifying properties used for traditional or short-term rentals.
Borrowers With Complex Income
An option for investors whose personal income may not fit traditional documentation requirements.
Investors Scaling Portfolios
Designed to support investors adding more rental properties to an existing portfolio.
These loans are intended for non-owner-occupied properties.
MAKING THE DECISION
Is a DSCR Loan Right for You?
A DSCR loan is the right fit if you want to finance an investment property without submitting personal income documentation. These loans typically require a higher down payment than conventional loans and a strong property cash flow profile.
We compare DSCR options across multiple lenders so you find the program that fits your investment strategy.
THE BROKER ADVANTAGE
One Broker. Many DSCR Loan Options.
A bank or direct lender is limited to its own DSCR programs and underwriting guidelines. For investment properties, requirements for rental income, property type, reserves, entity vesting, and DSCR ratios can vary significantly by lender.
Mortgage Marketplace is independent. We review DSCR options across our lender network based on your property, rental income, investment strategy, and financial profile. That gives you more choices and a clearer view of which program fits your scenario.
If another financing structure makes more sense for your investment, we will tell you that too.
DSCR LOAN FAQ
Questions Investors Ask About DSCR Loans
What is a DSCR loan?
A DSCR loan qualifies on the rental income the property generates rather than on your personal income. DSCR stands for debt service coverage ratio, which compares the property’s rental income to its total monthly payment. No tax returns, W-2s, or personal income documentation are required on most programs.
How is DSCR calculated?
Divide the property’s gross monthly rent by the total monthly payment, including principal, interest, taxes, insurance, and any association dues. Most lenders look for 1.0 or higher, and some accept lower with compensating factors.
Do I need to show my tax returns for a DSCR loan?
No. That is the defining feature of the program. Qualification rests on the property, your credit, and your down payment. This makes DSCR loans particularly useful for self-employed investors and for anyone whose returns show strong deductions against rental portfolios.
How much down payment does a DSCR loan require?
Typically 20 to 25 percent, with better pricing at larger down payments. The requirement varies with the DSCR ratio, your credit score, and the property type. Stronger coverage ratios generally unlock better terms.
Can I use a DSCR loan for a short-term rental?
Many lenders allow it, using either market rent or documented short-term rental income depending on the program and the location. Local regulations on short-term rentals matter as much as the loan guidelines. Tell us the market and the intended use and we will identify lenders that fit.
How many DSCR loans can I have?
Often more than conventional financing permits, since these loans are underwritten on the property rather than counting against a personal limit on financed properties. Investors building a portfolio frequently move to DSCR financing once conventional limits become a constraint.
Can I hold the property in an LLC?
Most DSCR programs permit vesting in a business entity, which is one reason investors prefer them over conventional financing. Requirements around the entity structure and personal guarantees vary by lender. Confirm your structure with us before you make an offer.
How long does it take to close a DSCR loan?
Closing takes 21 to 30 days in most cases, and often smoothly, because there is no personal income documentation to collect. The appraisal, which usually includes a rent schedule, is typically the pacing item. We are licensed in Oregon, California, Washington, Idaho, Texas, Florida, and Montana, with offices in Salem and Eugene, Oregon.
Compare Your DSCR Loan Options
DSCR loan requirements and terms vary by lender and property profile. We compare your options across multiple lenders so you see the real numbers before you decide.